- Reader’s Preface
- The Freedom Shift
- The Power of Choice
- Tiny Changes, Big Results: The Compound Effect of Small Wins
- Building the Freedom Fund
- Less Stuff, More Freedom: The Link Between Clutter and Wealth
- Know Your Worth: Unlocking Your Earning Potential
- The Hidden Forces Behind Your Spending Habits
- Designing a Life-Centered Budget
- Guarding Your Financial Future: Practical Steps for Security
- Rediscovering Joy Without Spending
- From “Can’t” to “Choose”: Taking Ownership of Your Financial Story
- Investing Made Simple: Building Wealth Without the Overwhelm
- Giving With Purpose: Aligning Charity With Your Values
- The Strength of Shared Goals: Finding Your Financial Tribe
- Redefining Wealth: What Success Really Means
- Dare to Dream: Turning Bold Ideas Into Reality
How much is enough?
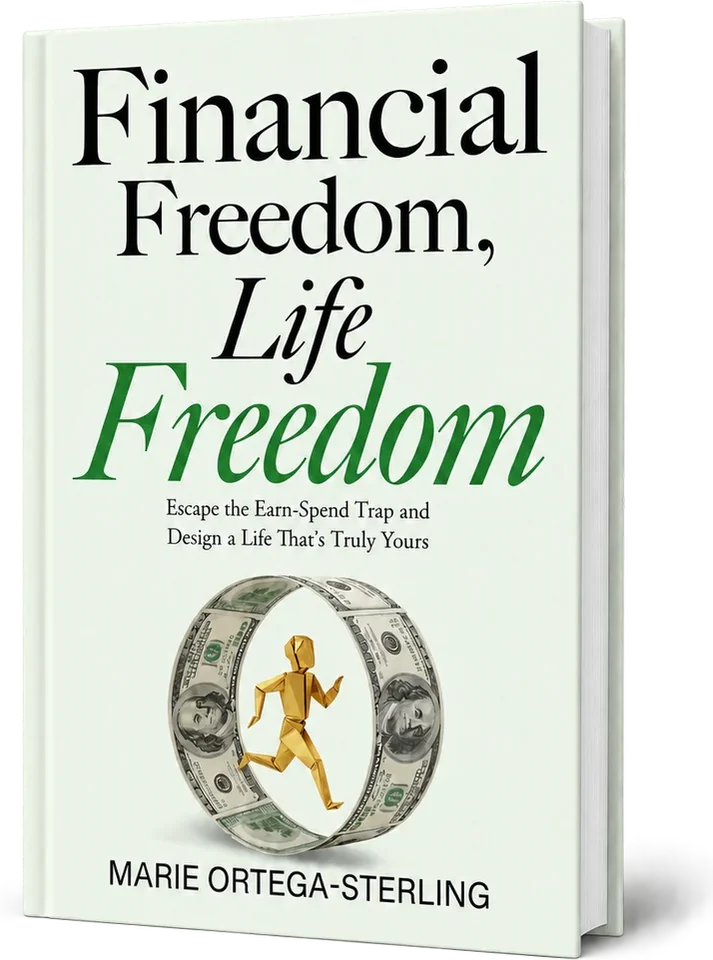
Financial Freedom, Life Freedom
Marie Ortega-SterlingFreedom Months = Freedom Fund ÷ monthly essentials
Freedom Fund
Monthly essentials
2 Freedom Months
Try it · Freedom Months
“Freedom Months is the number of months your Freedom Fund could cover your essentials if income stopped today.”
30 day experiments
Small, testable changes
- The 30-Day Clarity Experiment
- The 30-Day Small Wins Experiment
- The 30-Day Freedom Fund Plan
5.0
Read an excerpt
Freedom Months
Monthly essentials are the costs that keep your life running with safety and dignity. Housing belongs there, and so do groceries. Utilities, transportation, insurance, healthcare, minimum debt payments, childcare, and basic care responsibilities belong there. The restaurants and upgrades, the gifts and subscriptions, the travel and the shopping can all matter to you, and they still belong outside the essentials number. They may be valid and worth funding. They simply do not belong in the denominator of Freedom Months.
If your Freedom Fund holds $6,000 and your monthly essentials are $3,000, you have two Freedom Months. If your Freedom Fund holds $24,000 and your essentials are $4,000, you have six Freedom Months. The number turns a vague wish for security into something you can say out loud.
The headline number uses monthly essentials. Housing, groceries, utilities, healthcare, transportation, minimum debt payments, and the basic costs of caring for the people
who depend on you. If you want a stricter read, you can also divide the Freedom Fund by total monthly spending. Use that as an optional conservative check after you know your essentials number. The number you return to in this book is Freedom Months based on essentials.
Freedom Months changes the emotional weight of money. A $500 transfer is no longer a lonely act of discipline. It is part of a month you are buying back. A raise is no longer permission to upgrade everything. It is a chance to add distance between you and the next emergency. A cut expense is no longer deprivation when the money moves into time.
This is why the number comes first. Before you decide which expenses to cut or which goals to chase, you need to know how much time your current financial life has purchased. Jordan’s eighteen Freedom Months let him
negotiate from strength and watch the lock around his schedule loosen one transfer at a time. Lisa’s number below one month explained why every surprise felt dangerous.
Freedom Months also makes comparison less useful. Two people can earn the same salary and live in completely different levels of freedom. One earns $120,000 and stays under a single month, because almost every dollar already has somewhere to be. Another earns $120,000 and reaches six, because the life underneath the paycheck was kept lighter. The question is not who looks richer. The question is who can choose.
Use the number before major decisions. Before signing a lease, ask what the payment does to Freedom Months. Before accepting a promotion that requires longer hours, ask whether the extra income will widen your choices or fund a higher floor. Before buying the car, joining the club, or agreeing to another recurring payment, ask how
many months of freedom the commitment will cost. Some choices will still be worth it. The work is to see the trade clearly before it becomes your new normal.
Contents
About the book
Financial Freedom, Life Freedom starts with one number: Freedom Months, the number of months your Freedom Fund could cover your essentials if income stopped today.
Marie Ortega-Sterling shows how to work out that number, how to build the Freedom Fund in three layers, and how to design a life-centered budget around it.
Along the way are short experiments to try in your own life, among them the 30-Day Clarity Experiment, the 30-Day Small Wins Experiment and the 30-Day Freedom Fund Plan.
Details & ISBNs
- Subtitle
- Escape the Earn-Spend Trap and Design a Life That's Truly Yours
- Publisher
- Supercritical Books
- Published
- 2025
- Pages
- 234
- Paperback ISBN
- 978-1-968988-00-5
- Hardcover ISBN
- 978-1-968988-02-9
- Ebook ASIN
- B0FVVX7J4M

How much is enough?
The long answer is 234 pages.
Choose a format
Choose a store
Amazon Paperback Bookshop.org Supports indie shops Barnes & Noble US Buy direct From the printer Waterstones UK Thalia Germany
Prefer your local bookstore? Any shop can order it by ISBN.
978-1-968988-00-5